
Moving to a new country is a major milestone, and purchasing property there is an even bigger step. The Dutch housing market is dynamic, and the legal framework around real estate transactions is highly structured. In the Netherlands, the involvement of a civil-law notary is a mandatory legal requirement to finalize the purchase of a home.
Understanding the legal documentation is crucial to securing your investment and avoiding unexpected complications. De Boer Advies & Notariaat assists international clients throughout the entire property acquisition process, ensuring full legal compliance and clarity.
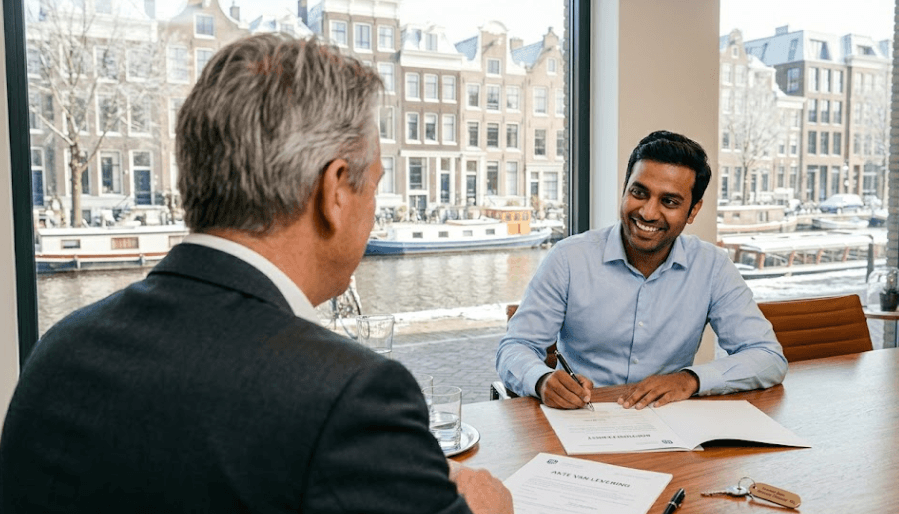 The Mandatory Role of the Dutch Notary
Unlike in some countries where real estate transfers are handled solely by real estate agents or specialized lawyers, Dutch law dictates that property ownership transfers must be executed by an impartial civil-law notary. The notary protects the interests of both the buyer and the seller, conducting necessary legal checks at the Land Registry (Kadaster) to ensure the property is free of undisclosed debts, seizures, or complex ground leases.
The Two Crucial Legal Deeds
When purchasing a home with financing, the notary will prepare and execute two distinct legal instruments:
1. The Deed of Transfer (Leveringsakte): This document legally transfers ownership of the real estate from the seller to you. It matches the conditions agreed upon in the initial purchase agreement.
2. The Mortgage Deed (Hypotheekakte): If you are financing your purchase, your lender requires this document to establish the property as collateral for the loan. By signing the mortgage deed, you agree to the binding obligations set by the bank.
Both documents must be signed by all parties at the notary’s office to make the transaction legally binding and allow for formal registration at the Land Registry.
Key Considerations for International Buyers
International clients often face unique financial and legal structures. For instance, younger buyers may qualify for a one-time exemption from the standard 2% transfer tax (overdrachtsbelasting), provided the property value falls below the statutory threshold (set at €525,000).
Furthermore, many professional fees associated with buying a primary residence—including notary fees for the mortgage document and mortgage advisory costs—are tax-deductible in the Netherlands. Ensuring these details are correctly processed in your final settlement statement (nota van afrekening) saves significant costs.
Frequently Asked Questions
Do I need a legal translator present during the signing at the notary office?
Yes. If you do not speak fluent Dutch, the law requires an official sworn translator to be present during the execution of the deeds. The notary will arrange this translator to interpret the legal content into English or your native language, ensuring you fully comprehend every obligation before signing.
When will the financial funds be transferred to the seller?
The notary holds all funds in a secure escrow account. Legally, the purchase price cannot be disbursed to the seller immediately upon signing. The notary must perform a post-signing registration check at the Land Registry to confirm no new liens or attachments were registered against the property at the last minute. Funds are typically disbursed two working days after execution.
Are notary fees for buying property in the Netherlands tax-deductible?
The fees charged by the notary for drawing up and registering the mortgage deed are fully tax-deductible if the property is your primary residence. However, the notary fees for the deed of transfer are not tax-deductible.
